
Key Takeaways
- Nexi shares dropped over 20% to record lows following Q4 revenue and EBITDA figures that fell short of analyst predictions.
- Management’s 2026 outlook suggests analysts may revise earnings estimates downward.
- Top-line growth is projected to remain flat in 2026, matching 2025’s 2.1% increase.
- The company forecasts €2.4 billion in excess cash generation between 2026–2028, with over €1.1 billion earmarked for shareholder returns.
- Management’s three-year roadmap aims to achieve mid-single-digit revenue growth by 2028.
Nexi, Italy’s leading payments processor, experienced a turbulent Thursday session. Shares plummeted more than 20% to unprecedented lows following the release of fourth-quarter results that missed expectations and a three-year strategic plan that analysts suggest could lead to earnings estimate reductions.
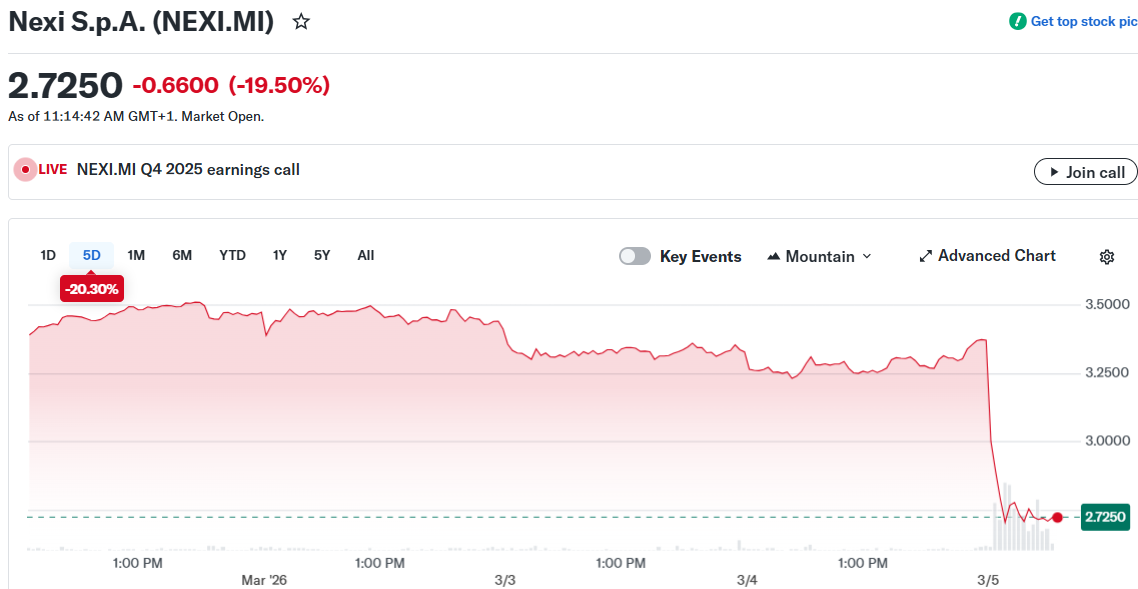
The market reaction was immediate and severe, though several analysts believe investors may have responded too harshly.
Fourth-quarter revenue remained unchanged at €942.5 million, landing approximately 1% below analyst expectations. EBITDA declined to €508.6 million, falling roughly 2% short of consensus estimates. Operating expenses increased year-over-year to €433.9 million.
The company’s performance was hampered by continued challenges from bank merchant-book M&A transactions and contract renegotiations. Management indicated these headwinds reached their maximum impact during Q4 2025, while cautioning that effects will persist throughout 2026 before gradually diminishing.
During a presentation in Milan, CEO Paolo Bertoluzzo spoke directly about investor expectations: “You don’t have to believe we can go to the moon.” He acknowledged that pricing concessions were granted to certain banks to secure contract renewals, and that the company continues to feel the effects of contracts lost in previous years.
2026 Outlook Shows Minimal Expansion
Management projects 2026 revenue performance will mirror 2025 levels, when the company achieved 2.1% top-line growth. EBITDA is anticipated to remain relatively stable as the company maintains investment in strategic priorities.
Morgan Stanley analyst Adam Wood stated the guidance “implies consensus downgrades” for 2026 and beyond. Jefferies characterized the results as “broadly in-line” while highlighting that 2026 targets “may feel more ambitious than at first glance.”
Jefferies analysts also expressed interest in learning how Nexi intends to “ignite growth without risking further contract losses.”
The competitive landscape provides important context. Emerging technology continues to reshape the payments sector, enabling nimble competitors to offer more competitive pricing than established firms. Traditional operators like Nexi, which expanded through acquisitions of banks’ payment operations, face particular vulnerability to this transformation.
Strategic Plan and Capital Allocation
The company’s updated medium-term strategy emphasizes targeting mid-sized businesses to protect market position, with full-year revenue growth targeted to reach mid-single digits by 2028. EBITDA margin improvement is anticipated by the conclusion of the plan period.
Management forecasts approximately €2.4 billion in excess cash generation spanning 2026–2028, including roughly €750 million in the current year after accounting for strategic investments and increased tax obligations.
The company announced a proposed dividend of €0.30 per share, with intentions to increase the payout by a minimum of 5% annually throughout the next three years. Cumulative distributions to shareholders are projected to surpass €1.1 billion by 2028.
Bertoluzzo positioned the capital return strategy as evidence of management’s confidence in the business model’s durability during what the company characterizes as a “transition year.”
Despite the substantial share price decline, certain analysts observed that the 2025 earnings shortfall was relatively minor and that medium-term projections remained reasonably aligned with previous expectations.
According to Nexi, Q4 2025 represented the maximum impact from contract renegotiations, with the burden anticipated to progressively diminish going forward.



