
TLDR
- Crude oil climbed more than 36% over seven days, surpassing $91 per barrel following Iran conflict that blocked Strait of Hormuz traffic
- Year-to-date losses reach 1.5% for the S&P 500; Nasdaq trades 3.7% lower since the start of January
- February employment showed a decline of 92,000 positions, sharply missing expectations that called for 55,000 gains
- Earnings calendar brings Oracle on Tuesday; Adobe and Hewlett Packard Enterprise follow later in the week
- Wednesday brings Consumer Price Index figures and Friday delivers PCE data before the Federal Reserve meets next week
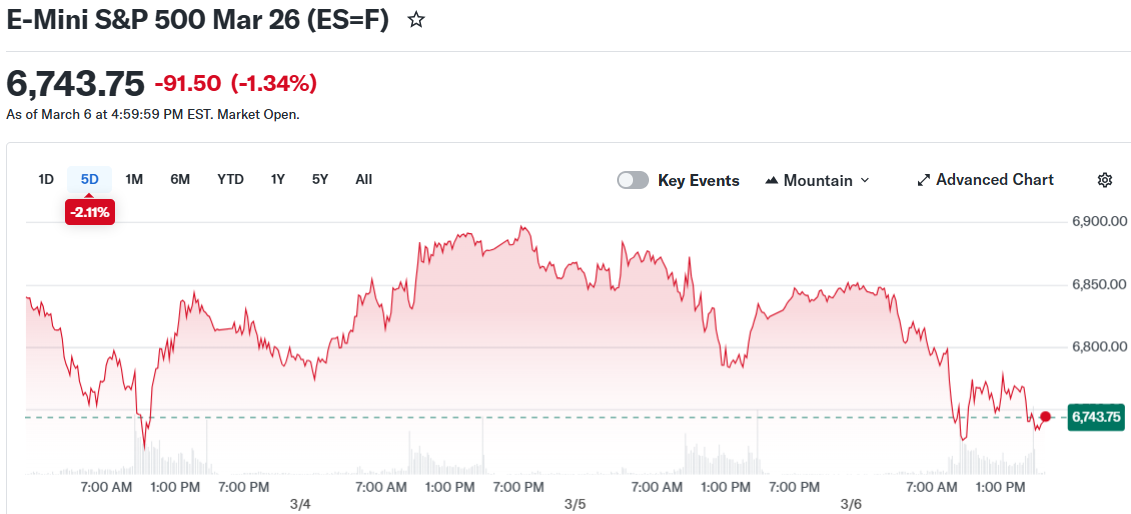
Friday’s trading session ended with significant losses across major US equity benchmarks, concluding one of 2026’s most challenging weeks. The S&P 500 declined 1.3% during Friday’s session, extending its yearly decline to 1.5%. The Nasdaq fell 1.6% Friday, bringing its loss from January 1 to 3.7%. The Dow Jones Industrial Average dropped approximately 450 points.
The Iranian conflict stands as the primary force behind current market turbulence, severing oil transport through the Strait of Hormuz. This critical waterway typically facilitates approximately 20% of global seaborne petroleum shipments.
Current conditions have left roughly 16 million barrels without viable delivery routes, based on figures from Vortexa. Storage facilities have reached capacity. Production operations face cutbacks. Oil prices have jumped over 36% across seven trading days, crossing $91 per barrel — marking the sharpest weekly advance dating back to at least 1985.
Vikas Dwivedi, global energy strategist at Macquarie, cautioned that “a few weeks of Hormuz closure will create a domino effect of events that could push crude to $150 or higher.” Market analysts increasingly view that price level as achievable.
Inflation and the Fed
The timing of this energy price surge poses significant challenges for Federal Reserve policymakers. San Francisco Fed president Mary Daly remarked to CNBC on Friday that “the oil price shock, depending on how long it lasts, is a real thing.”
Goldman Sachs projects that sustained elevated oil levels over multiple months could drive headline inflation back toward 3% on a year-over-year basis. The Federal Reserve maintains a 2% inflation objective.
Ten-year Treasury yields have risen past 4.14%. Market participants have tempered rate cut expectations while evaluating how rising energy costs might affect inflation trends. Fed officials including Neel Kashkari and John Williams indicated they need more time to gauge the complete impact.
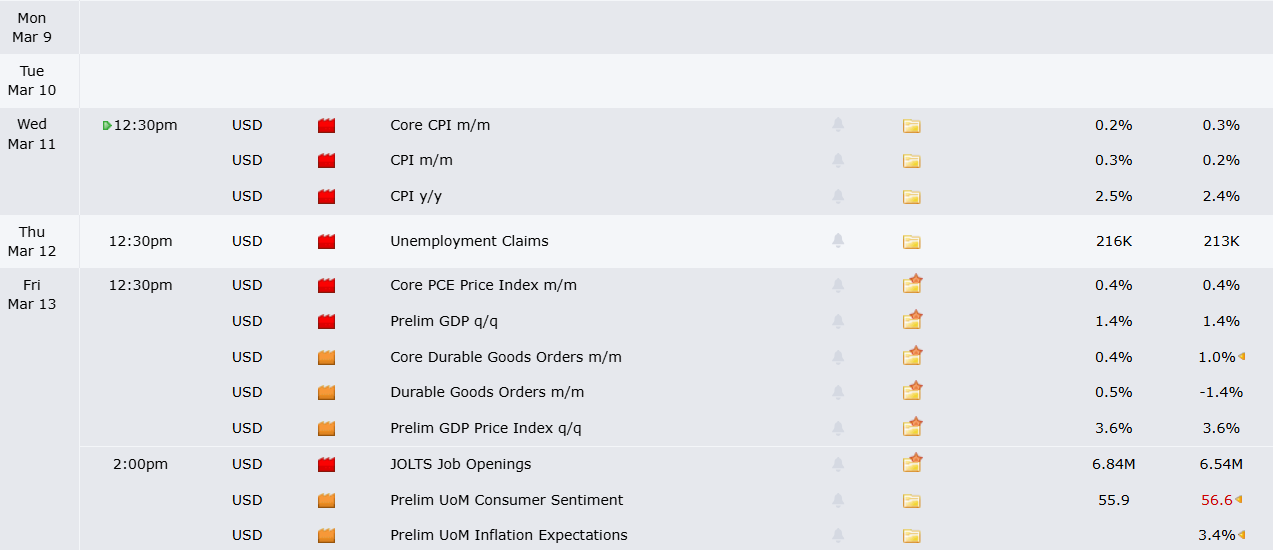
Wednesday delivers the February Consumer Price Index while Friday brings the January Personal Consumption Expenditures index, offering crucial inflation readings before the Federal Reserve convenes next week.
Jobs Miss Adds to Concern
February’s employment report intensified market anxiety. Employment declined by 92,000 positions, falling far short of projections calling for 55,000 additions. The unemployment rate climbed to 4.4%, rising from January’s 4.3%.
BREAKING: The US economy unexpectedly LOSES -92,000 jobs in February, below expectations of a +58,000 gain.
The unemployment rate was 4.4%, above expectations of 4.3%.
This marks just the 2nd monthly job loss since the 2020 pandemic.
The US labor market is clearly weakening.
— The Kobeissi Letter (@KobeissiLetter) March 6, 2026
Certain economists highlighted temporary disruptions, referencing a Kaiser Permanente labor action that removed 37,000 positions from the tally. BNP Paribas economist Andrew Husby attributed the outcome to “special factors.”
Alternative interpretations emerged. Gina Bolvin of Bolvin Wealth Management identified “a bifurcated market — slower macro growth paired with accelerating technological transformation.” Jack Dorsey’s Block eliminated 4,000 positions in February, with company leadership linking the reductions directly to artificial intelligence adoption.
#earnings for the week of March 9, 2026 https://t.co/hLn2sKQhEY $ORCL $ADBE $NIO $PATH $RBRK $S $KSS $AVAV $CASY $HPE $ZIM $VOYG $NKTR $DDD $BETA $ZVRA $SERV $FCEL $CPB $ULTA $NSK $CXM $TTAN $ACCO $MTN $YEXT $AUNA $DKS $KFY $SFIX $GNS $NYAX $KRO $LFMD $UMAC $SPRY $STXS $SBET… pic.twitter.com/No54dcR5hZ
— Earnings Whispers (@eWhispers) March 6, 2026
Oracle delivers quarterly results Tuesday. Shares have declined more than 50% from September peaks. The enterprise software company recently unveiled plans to allocate $50 billion toward AI data center infrastructure. Adobe and Hewlett Packard Enterprise join the earnings calendar this week, along with Dollar General, Li Auto, and Nio.



