
Key Takeaways
- Major index futures advanced Thursday morning following a strong showing from Big Tech earnings reports
- Alphabet and Amazon delivered impressive results that sent their stock prices higher; Meta and Microsoft saw muted responses
- AI capital expenditure projections from four major technology companies reached $725 billion for 2025
- Crude oil jumped to a four-year peak above $126 per barrel on Middle East military concerns before retreating to under $117
- March core PCE inflation advanced 0.3% month-over-month, topping forecasts; first quarter GDP expanded at 2% annualized pace
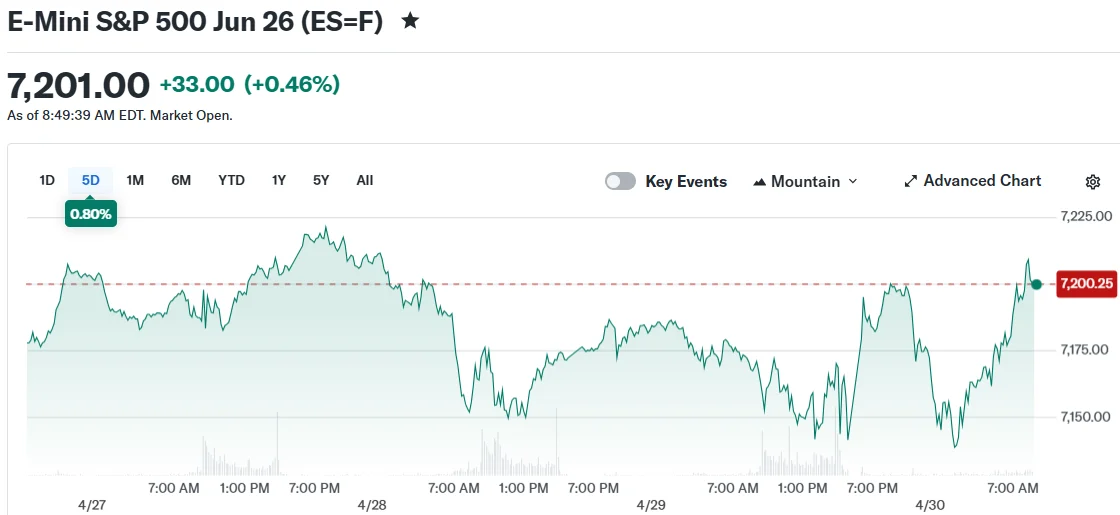
Stock index futures posted solid gains Thursday morning as investors digested a flood of quarterly reports from technology giants and new macroeconomic indicators. Dow futures advanced approximately 0.6%, with S&P 500 and Nasdaq 100 futures showing increases ranging from 0.3% to 0.7%.
The upward momentum followed Wednesday’s earnings releases from four technology powerhouses. Alphabet and Amazon surpassed analyst projections, triggering share price appreciation. Meta and Microsoft received lukewarm market reactions despite delivering respectable financial performance.
Meta shares declined after the company’s infrastructure investment guidance fell short of Wall Street expectations. Microsoft dipped roughly 1% even after exceeding both top-line and bottom-line forecasts.
The market response varied across individual names, yet the collective artificial intelligence spending forecast from these four corporations totaled $725 billion for the current year. This substantial commitment boosted semiconductor stocks and maintained bullish investor momentum entering Thursday’s session.
Apple’s earnings report arrives after Thursday’s closing bell. Analysts are eager for management commentary on how substantial AI infrastructure investments are impacting overall revenue performance.
Crude Prices Surge Then Retreat on Geopolitical Developments
Oil prices touched their loftiest levels since 2022 during early Thursday trading. Brent crude jumped 7% to surpass $126 per barrel following an Axios article suggesting President Trump is evaluating potential military responses targeting Iran.
Prices retreated to below $117 as the trading session progressed and initial market reactions moderated. The volatility introduced additional complexity to an already event-heavy morning for equity markets.
March’s core PCE index, the Federal Reserve’s favored inflation gauge, increased 0.3% versus February’s reading. The annual rate reached 3.2%, aligning with year-over-year projections while exceeding the monthly consensus estimate.
First quarter GDP expanded at a 2% annualized clip, falling short of the 2.3% consensus forecast. These economic indicators provided investors with updated perspectives on underlying economic conditions as the second quarter begins.
Federal Reserve Maintains Policy Stance as Powell Discusses Tenure
The Federal Reserve maintained its current interest rate policy during Wednesday’s meeting, matching widespread market expectations. Chair Jerome Powell indicated his intention to complete his existing term.
Powell’s remarks arrived amid continued internal Fed discussions regarding inflation policy direction. Thursday’s PCE release contributed fresh data points to ongoing deliberations about potential future rate adjustments.
Market participants are directing considerable attention toward Apple’s upcoming earnings announcement. Investors seek evidence that massive AI-related capital outlays are generating meaningful revenue growth at the technology behemoth.
The Dow, S&P 500, and Nasdaq all indicated positive openings based on early Thursday morning futures activity.



