
Key Highlights
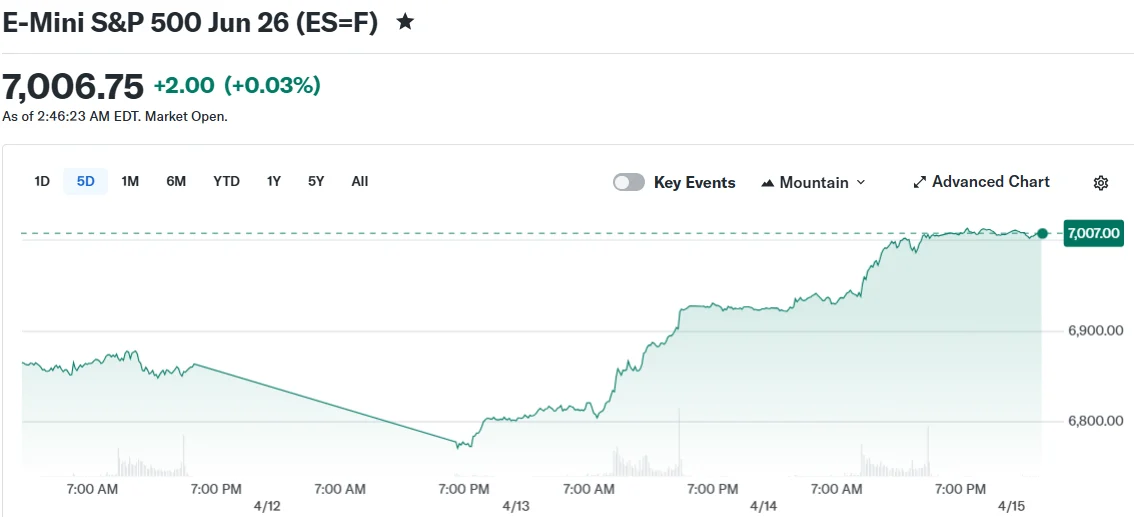
- Equity futures trading near unchanged levels Wednesday following Tuesday’s robust advance
- Nasdaq Composite has posted gains across 10 consecutive trading days, marking its longest rally since November 2021
- S&P 500 index positioned merely 0.2% away from reaching an all-time record
- President Trump indicated Middle East tensions “close to over,” strengthening market sentiment
- Major financial institutions Bank of America and Morgan Stanley scheduled to release quarterly results Wednesday
U.S. equity futures maintained a steady position Wednesday morning following an impressive rally that has brought benchmark indices within striking distance of historic peaks.
Contracts tied to the S&P 500, Dow Jones Industrial Average, and Nasdaq 100 showed minimal movement ahead of the opening bell. Trading activity suggested investors were consolidating recent advances after multiple sessions of robust performance.
The Nasdaq Composite has delivered positive returns for 10 consecutive trading sessions, representing its most extended period of uninterrupted gains since November 2021.
The S&P 500 concluded Tuesday’s session positioned just 0.2% beneath its record high. The benchmark index has advanced in nine out of the previous 10 trading days.
Much of the recent market strength stems from growing confidence surrounding a possible resolution to tensions between the United States and Iran. Market participants have become increasingly hopeful that diplomatic efforts will yield a lasting agreement.
President Trump reinforced this positive outlook during a Tuesday evening appearance. Speaking with Fox Business, he characterized the situation in the Middle East as “close to over.”
NEW: President Trump says the war with Iran is "close to over."
Full interview airs on @MorningsMaria on Fox Business at 6 a.m. pic.twitter.com/7YqjbHW3Fy
— Fox News (@FoxNews) April 15, 2026
Trump further informed reporters that diplomatic discussions could resume within a two-day timeframe. He indicated that extending the current two-week ceasefire might prove unnecessary.
Market strategists note that investors will carefully monitor developments regarding these negotiations. Continued advancement toward a peaceful resolution could provide the momentum needed to propel equities to unprecedented levels.
“As the path continues to point firmly towards durable de-escalation, risk appetite should remain underpinned, with any equity dips continuing to be viewed as buying opportunities,” said Michael Brown, research strategist at Pepperstone.
Oil prices showed modest gains Wednesday morning. Brent crude futures advanced 0.4% to reach $95.11 per barrel, while West Texas Intermediate climbed 0.2% to $91.27 per barrel.
Decreasing energy costs from recent peaks could alleviate inflationary pressures. Such developments would likely benefit risk-oriented investments across the board.
The U.S. dollar traded unchanged versus a basket of major global currencies. The benchmark 10-year Treasury note maintained its yield at 4.25%.
Earnings in Focus
Investor attention is shifting toward corporate financial results. Bank of America and Morgan Stanley are both set to announce quarterly performance Wednesday morning.
Financial sector results have drawn significant scrutiny during this reporting period. Earnings from leading banking institutions may provide investors with valuable insights into broader economic conditions.
What to Watch
Market participants await additional updates regarding the Iran diplomatic situation. Concrete evidence of progress in peace negotiations could serve as the trigger that elevates stocks to fresh all-time records.
The S&P 500 remains positioned just slightly below its late-January summit. A single robust trading session could carry the index into uncharted territory.



