
Key Highlights
- Chairman Chey Tae-won of SK Group projects the worldwide memory chip supply shortage will extend through approximately 2030.
- Artificial intelligence applications requiring high-bandwidth memory (HBM) are consuming substantial wafer quantities, fueling the supply gap.
- Current wafer availability trails demand by over 20% throughout the semiconductor industry.
- SK Hynix commands a 57% market share in HBM production and holds 32% of worldwide DRAM capacity.
- The company is exploring the possibility of establishing an American Depository Listing for US market access.
SK Hynix Chairman Chey Tae-won captured industry attention Monday when he projected that worldwide memory chip supply constraints could persist for an additional four to five years. His remarks came during media engagements at Nvidia’s GTC conference taking place in San Jose, California.
Chey identified artificial intelligence as the primary driver. “AI actually wants to have a lot of HBM, and once you make the HBM… we have to use a lot of wafers,” he explained to reporters, according to Reuters.
The fundamental challenge is straightforward: wafer production capacity remains insufficient. Chey indicated that the disparity between available supply and market demand for foundational wafers used in chip manufacturing exceeds 20% industry-wide. This represents a structural imbalance requiring years to resolve.
Expanding wafer manufacturing capacity demands considerable time — Chey estimated a minimum of four to five years — establishing a baseline for when the shortage might begin easing. This projection suggests 2030 as the earliest point when supply could align with demand.
Upward Price Pressure Already Visible
The supply constraints are already impacting current market conditions. Server memory chip pricing jumped between 60% and 76% during Q4 2025, data from Counterpoint Research shows. Analysts anticipate continued price increases extending into Q1 2026.
SK Hynix has emerged as a major beneficiary of these price dynamics. The manufacturer leads the HBM market with a commanding 57% share while maintaining second position in global DRAM with 32% market share, according to Counterpoint figures.
The company serves as the principal HBM provider to Nvidia, whose processors power the AI infrastructure expansion generating this unprecedented demand.
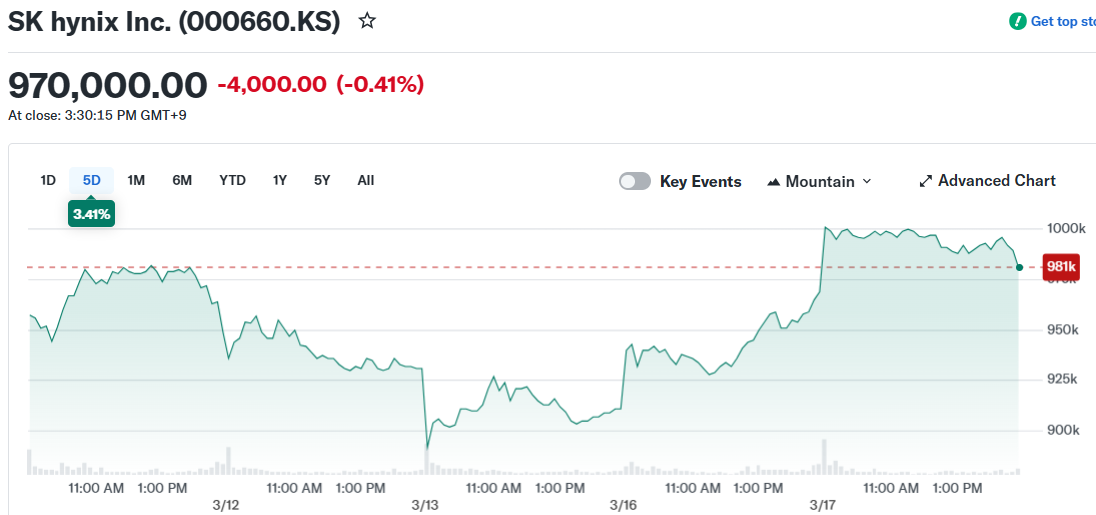
SK Hynix shares advanced more than 2% Tuesday in response to the chairman’s projections.
Chey indicated the company plans to develop strategies aimed at supporting DRAM price stability, though concrete details remain to be disclosed.
Exploring American Depository Receipt Options
In related developments, Chey acknowledged that SK Hynix is evaluating the feasibility of an American Depository Receipt listing. This structure would enable US-based investors to purchase SK Hynix shares directly through American exchanges, bypassing Korean market access requirements.
The company has yet to announce specific timelines or formal commitments regarding this initiative.
Samsung Electronics alongside American-based Micron complete the leading trio in global memory production. Micron holds third position worldwide in memory and storage chip manufacturing, following Samsung and SK Hynix.
Chey’s observations arrive as the artificial intelligence sector continues generating unprecedented demand patterns throughout semiconductor supply networks. SK Hynix equity has appreciated substantially across the past three years concurrent with expanding AI-related procurement.
Counterpoint research indicates server memory demand has grown steadily alongside AI infrastructure investment, with momentum showing no indication of moderating.
Current market data positions server memory pricing in firmly positive growth territory entering 2026, with additional increases anticipated as supply limitations persist.



