
Key Takeaways
- Lufthansa considers grounding up to 40 aircraft (approximately 5% of total fleet) in response to Middle East fuel supply constraints
- Closure of the Strait of Hormuz has disrupted global jet fuel supply chains, with Europe sourcing approximately 50% from Persian Gulf facilities
- Morgan Stanley shifts DLAKY rating from “overweight” to “equal-weight,” reducing 2026 EBITDA projection by 17%
- Airline faces €1.6bn increase in fuel expenses, driving approximately €800m reduction in EBITDA
- Load factor projections decline roughly 2% year-over-year beginning Q3 2026, while capacity expansion revised downward from 4% to 2.5%
Lufthansa faces mounting pressure this week as Morgan Stanley’s downgrade combines with escalating jet fuel supply constraints. The German airline stands among Europe’s most vulnerable carriers to current energy market volatility, with financial projections now reflecting that exposure.
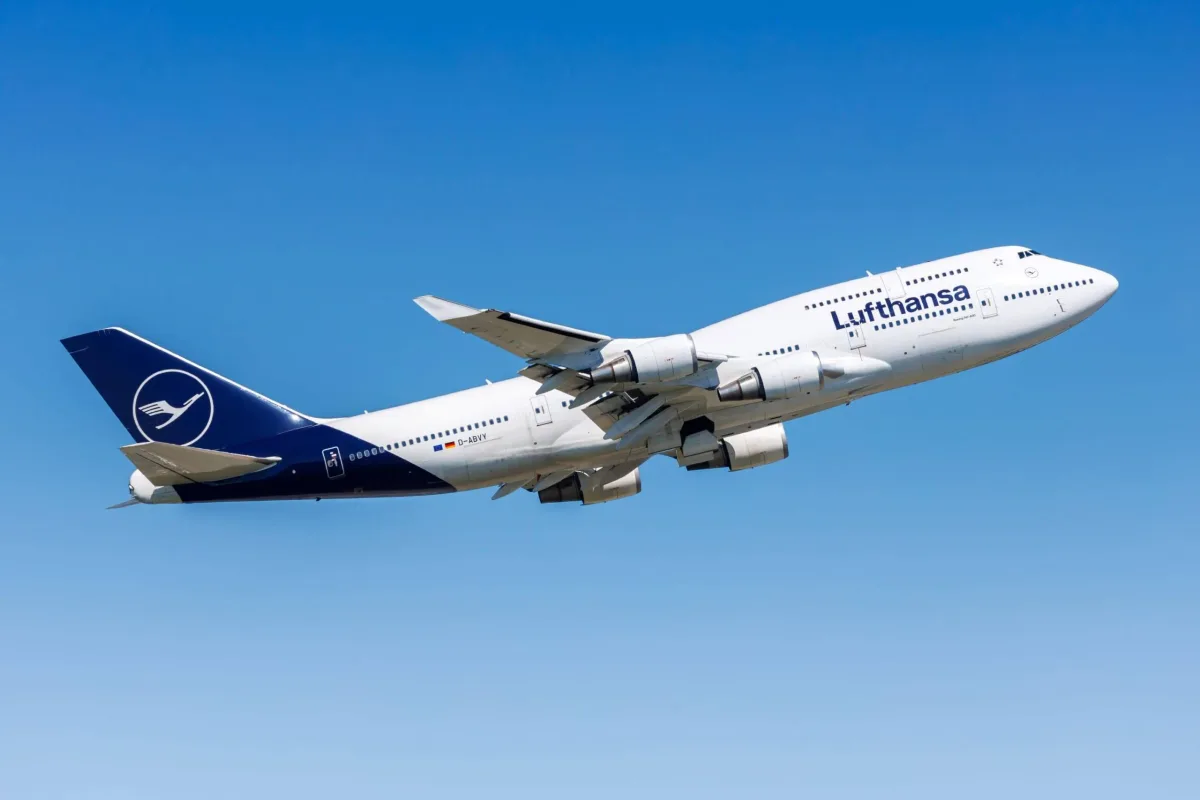
CEO Carsten Spohr has instructed leadership teams to prepare operational contingency strategies across multiple disruption scenarios. The most significant measure under consideration involves grounding up to 40 aircraft, representing roughly 5% of total fleet capacity. Leadership evidently favors proactive cost management over reactive demand adjustments.
The core issue stems from the Strait of Hormuz closure, which serves as a vital transit corridor for worldwide jet fuel distribution. Asian refineries have begun scaling back production accordingly, with Europe facing particularly acute vulnerability — approximately half of all EU and UK jet fuel originates from Persian Gulf sources.
The supply constraint extends beyond simple pricing dynamics. Availability uncertainty creates hedging complexities that prove especially challenging for an airline already trailing competitors in fuel risk management strategies.
Broker Lowers Rating and Revises Financial Projections
Morgan Stanley adjusted Lufthansa’s rating to “equal-weight” from “overweight” on Wednesday, pointing to diminished earnings prospects and inferior fuel hedging positions compared to rivals including IAG and Air France-KLM.
The firm reduced its 2026 EBITDA forecast for Lufthansa by 17% — substantially more aggressive than the 6% adjustment for IAG or 10% revision for Air France-KLM. Hedging strategy accounts for much of this disparity. Morgan Stanley characterized Lufthansa’s fuel hedging approach as “less attractive vs. peers.”
In absolute terms, the bank projects a €1.6bn fuel cost increase for the fiscal year, driving approximately €800m in EBITDA erosion compared to previous estimates.
Capacity expansion targets also received downward adjustment, moving from 4% to 2.5%, while load factor expectations show approximately 2% year-over-year compression starting Q3 2026.
Fare Increases Provide Limited Relief
Regarding revenue generation, Morgan Stanley anticipates Lufthansa will implement meaningful fare increases. Passenger yield projections show +7% growth in Q2, +11% in Q3, and +11% in Q4 of 2026.
These revenue improvements will only partially compensate for elevated fuel expenses. Legacy carriers typically command stronger pricing authority than budget competitors, yet Lufthansa still trails European counterparts in managing fuel cost exposure.
Morgan Stanley noted that Lufthansa’s year-to-date decline of approximately 9% compares favorably to the roughly 16% depreciation observed at IAG and Air France-KLM, describing this performance spread as “a disconnect we view as unjustified.”
Shares rallied as much as 8.1% during early Frankfurt trading on Tuesday following disclosure of the contingency planning — after declining approximately 16% year-to-date through that session. The downgrade and ongoing fuel supply concerns continue to weigh on equity performance.



