
TLDR
- Bitcoin maintained support above $70,000 Friday, securing approximately 7% gains for the week following early price swings
- International equity markets bounced back from midweek losses, with S&P 500 futures advancing to approximately 6,840
- Crude oil experienced a surge exceeding 16% this week following Iran’s blockade of tankers in the Strait of Hormuz
- U.S. Treasury yields advanced for four consecutive sessions, with the 10-year rate moving from 3.93% to 4.15%
- Market expectations for Federal Reserve rate reductions fell to below 50-50 odds for two cuts this year, declining from approximately 80%
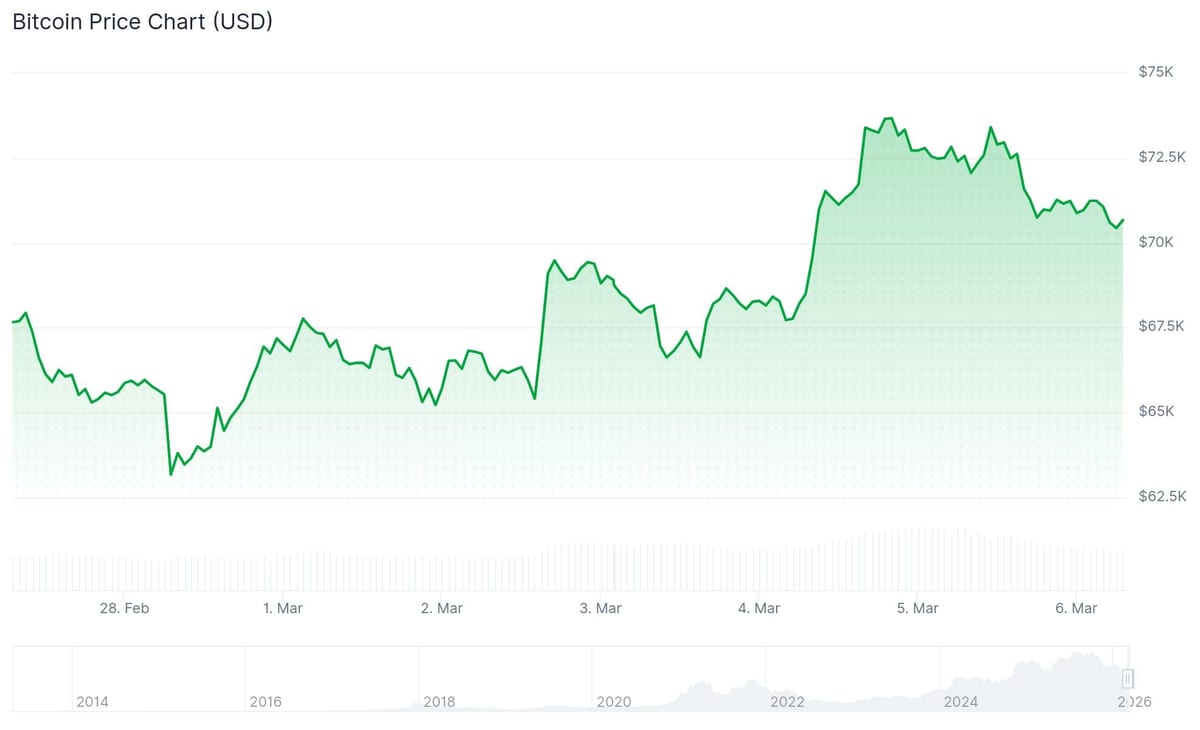
Bitcoin maintained its position above $70,000 on Friday as international equity markets found stability following a volatile week shaped by the escalating U.S.-Israel-Iran conflict. Bond markets, however, continue painting a contrasting picture.
The trading week opened with aggressive selling across risk assets following Iran’s decision to block oil tankers in the Strait of Hormuz, a critical passage that handles approximately 20% of global oil supply. This action propelled crude prices upward by more than 16% for the week, marking their largest weekly advance since March 2022.
How high will inflation go?
According to a recent Fed study, every $10 rally in oil prices can increase inflation by ~20 bps.
Oil has already surged from $55 to $80 per barrel, implying +50 bps of inflation pressure.
This could push CPI from 2.4% to ~2.9%.
When oil prices… https://t.co/M4aEHSr32e pic.twitter.com/GL0IiBQdiB
— Adam Kobeissi (@TKL_Adam) March 5, 2026
Bitcoin declined to approximately $65,000 over the weekend before staging a recovery. The digital asset briefly touched $74,000 on Wednesday, then retreated to $70,182 by Friday morning, remaining positioned for a weekly gain of approximately 7%.
Equity markets traced a similar trajectory. S&P 500 futures descended to a multi-week low of 6,718 on Tuesday before rallying to around 6,840. The Dow declined over 2% for the week and moved into negative territory for 2026. The Nasdaq demonstrated greater resilience, tracking toward a modest weekly gain.
The U.S. acted to stabilize petroleum markets by announcing naval escorts for tankers through the strait, which helped ease initial concerns. Energy prices, however, remained elevated.
Treasury Yields Continue Ascending
The more significant concern for markets centers on developments in fixed income markets. The 10-year U.S. Treasury yield advanced for four consecutive sessions, climbing from 3.93% to 4.15%. The two-year yield jumped from 3.37% to nearly 3.60%.
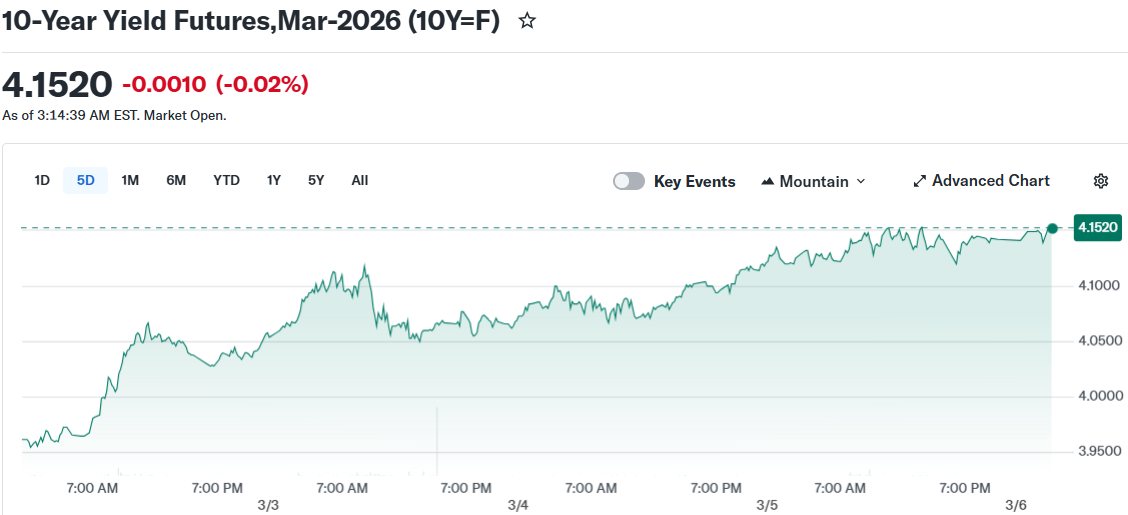
Ascending yields demonstrate increasing concern that elevated oil prices will reignite inflation, constraining the Federal Reserve’s ability to implement interest rate reductions.
Prior to the conflict’s emergence, traders assigned nearly an 80% probability to two Fed rate cuts this year. That figure has now fallen below 50%.
Bryan Tan, a trader at Wintermute, said the rates market is “revealing the tension in this rally,” pointing to strong economic data alongside an inflationary energy shock as a combination that could keep the Fed on hold longer.
Recent U.S. economic indicators reinforced that outlook. The ISM Services index registered 56.1 in February, demonstrating ongoing expansion. The ADP payrolls report revealed 63,000 private sector jobs added, exceeding the 50,000 forecast and marking the strongest reading since July 2025.
Alternative Cryptocurrencies and Additional Assets Face Headwinds
Most prominent altcoins declined on Friday. Ethereum retreated 3% to $2,069. XRP decreased 1.8% to $1.39. Solana slipped 1.6%, while Cardano and Polygon each declined 2.5%. Dogecoin also fell 1.8%.
Gold tracked toward a weekly decline despite continuing geopolitical tensions, pressured by a strengthening U.S. dollar.
Analyst Jack Prandelli observed that oil prices historically advance 20–30% within 60 days following a significant geopolitical disruption, suggesting markets may be underestimating the supply risk.
Market attention now shifts to Friday’s nonfarm payrolls report. Economists anticipate job growth of approximately 55,000, down from 130,000 in January. A stronger-than-anticipated number could drive yields higher still.



