
Key Takeaways
- JPMorgan revised its 2026 S&P 500 year-end forecast downward from 7,500 to 7,200
- Crude oil has rallied more than 40%, with production disruptions reaching 8 million barrels daily
- Market participants are employing hedging strategies while maintaining near-record gross leverage levels
- Sustained oil prices around $110 per barrel could trigger earnings estimate reductions of 2–5%
- JPMorgan recommends exposure to Defense, Energy, Utilities, and Cybersecurity industries
JPMorgan has revised its year-end 2026 forecast for the S&P 500 downward to 7,200, a reduction from its previous 7,500 projection. The financial institution believes equity markets are underestimating threats stemming from regional conflicts, escalating energy costs, and excessive market optimism.
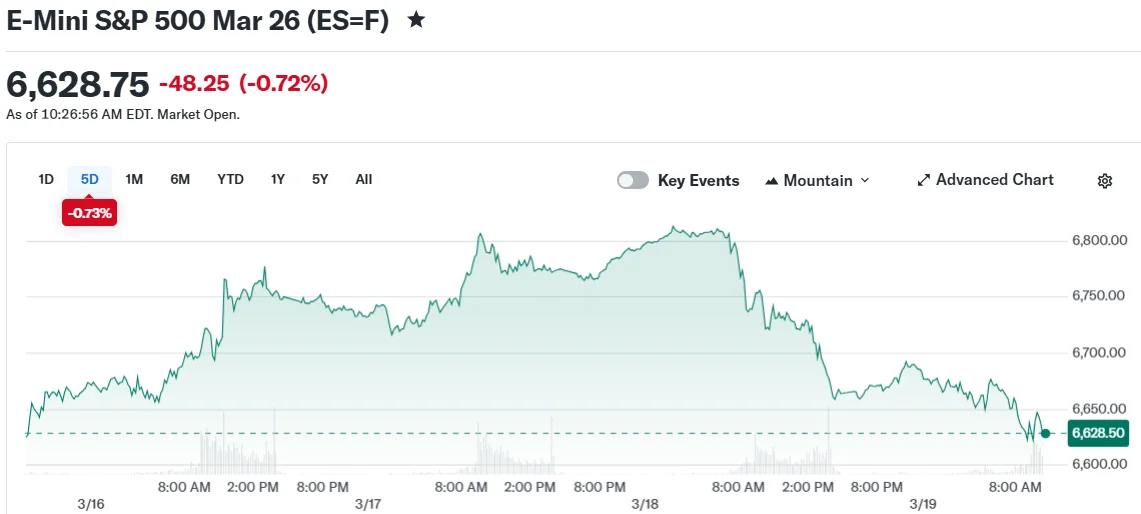
Analyst Dubravko Lakos-Bujas authored the research note. He observed that the S&P 500 has declined approximately 3% despite crude oil rallying over 40%.
He credited this relative stability to capital flows seeking safe-haven assets within U.S. markets. However, he cautioned that this apparent resilience could be masking underlying vulnerabilities.
According to Lakos-Bujas, market participants have primarily adopted hedging tactics instead of outright position liquidation. Gross leverage metrics remain near the 95th percentile when viewed across historical data, representing a notable warning signal.
JPMorgan believes equity markets are embedding expectations for a swift resolution to regional hostilities and the resumption of normal shipping routes. The firm characterized this scenario as carrying substantial risk.
Historical patterns show that oil and equities typically exhibit inverse correlation once petroleum prices surge beyond 30%. That critical level has already been exceeded.
Production Disruptions Reach Unprecedented Scale
Oil supply interruptions have climbed to 8 million barrels daily, marking the largest disruption on record. JPMorgan projects this figure could escalate to 12 million barrels per day, equivalent to approximately 11% of worldwide production capacity.
The bank identified the primary danger as extending beyond inflationary pressures. The more significant concern involves prolonged supply constraints that suppress consumption, thereby dragging down economic growth, corporate revenues, and profit margins through what analysts describe as “forced demand destruction.”
Should crude oil maintain levels near $110 per barrel, JPMorgan anticipates Wall Street’s consensus earnings projections for the S&P 500 could face downward revisions ranging from 2% to 5%.
Additional challenges confront the benchmark index. Lakos-Bujas highlighted emerging strains within private credit markets, indications that artificial intelligence momentum is cooling, and deteriorating consumer purchasing power.
Critical Technical Levels Under Scrutiny
Should the S&P 500 breach its 200-day moving average, JPMorgan identifies minimal technical support until the 6,000–6,200 zone. Such a move would constitute a significant retreat from present valuation levels.
The institution stops short of predicting a market collapse, while emphasizing the importance of defensive positioning. It advocates for portfolio rotation toward Low Volatility and Quality Growth equities.
Recommended sector allocations outlined in the analysis include Defense, Energy, Utilities, Materials, Cybersecurity, and Hyperscalers.
While the research note made no explicit reference to digital assets, elevated petroleum prices and macroeconomic instability have traditionally impacted speculative investments including Bitcoin and alternative cryptocurrencies.
JPMorgan’s updated 7,200 target represents the firm’s most recent official projection as of March 19, 2026.



