
TLDR
- Brent crude reached $104.76/barrel following U.S.-Israel strikes on Iran that disrupted Strait of Hormuz traffic
- Approximately 20% of global oil supply flows through the Strait, where shipping activity has largely ceased
- European oil majors could achieve free cash flow yields around 14% at sustained $100 oil prices, according to JPMorgan
- Shell, TotalEnergies, Eni, and Galp lead JPMorgan’s investment recommendations
- While the Fed maintains current rates, elevated oil prices may push back anticipated rate reductions
Wall Street analysts are turning their focus toward European energy majors as oil prices breach the $100 mark, propelled by supply concerns stemming from military operations between the U.S., Israel, and Iran.
Brent crude futures advanced 1.3% to reach $104.76 per barrel during Wednesday trading, recovering from earlier session declines. The upward movement persisted despite an agreement between Iraq and Kurdish officials to restart exports via Turkey’s Ceyhan terminal, which provided modest market support.
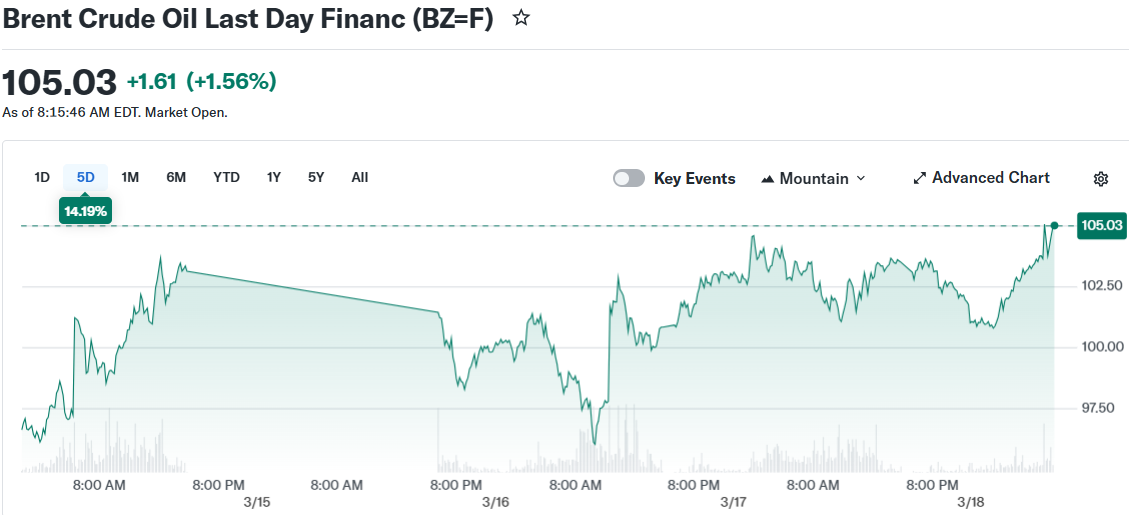
West Texas Intermediate declined 0.6% to settle at $94.95 per barrel during the same period.
Military conflict entering its third week has brought shipping through the Strait of Hormuz to a virtual standstill. U.S. forces have conducted strikes against Iranian coastal installations housing cruise missile systems capable of threatening vessels navigating the strategic waterway.
Approximately 20% of the world’s petroleum passes through the Strait of Hormuz. Extended interruptions in this corridor carry significant implications for global energy distribution.
JPMorgan analyst Matthew Lofting characterizes the financial implications for European petroleum companies as “clearly positive.” His analysis shows that production losses tied to Hormuz disruptions reduce company cash flow by approximately $6 per barrel, reaching up to $10 for entities with concentrated exposure.
This figure stands against roughly $30 in price appreciation since hostilities commenced, indicating the revenue benefit substantially exceeds volume-related losses for most operators.
Free Cash Flow Yields Could Hit 14%
Lofting’s projections indicate free cash flow yields for European energy stocks may climb from the current 10% under prevailing forward curves to approximately 14% within a persistent $100 oil scenario. He characterizes current valuations as remaining “modestly cheap” relative to metrics observed during the 2022 energy crisis.
European oil sector equities have already appreciated more than 10% since conflict eruption.
JPMorgan identifies Shell, TotalEnergies, Eni, and Galp as premier sector opportunities. The investment bank points to robust price elasticity, extended production horizons, and attractive valuations as primary selection factors.
Eni and Shell receive particular emphasis for their elevated oil price sensitivity. Galp’s leverage potential appears underrepresented in immediate financial projections.
TotalEnergies, Shell, and OMV maintain the most substantial Middle Eastern asset portfolios. Equinor, Repsol, and Galp carry minimal direct regional exposure, potentially demonstrating enhanced responsiveness to immediate price fluctuations.
JPMorgan anticipates robust trading operations will contribute additional gains, projecting approximately $4 billion in potential benefits for Shell through this channel alone.
Lofting identifies potential windfall taxation as one notable risk factor, drawing on 2022–23 precedents. His models incorporate an additional 5% levy on cash flows as a possible constraint.
Fed Meeting Adds Uncertainty
Market participants approached Wednesday’s Federal Reserve announcement with caution. Consensus expectations point toward rates remaining unchanged within the 3.5% to 3.75% range.
Fed Chair Jerome Powell, whose tenure concludes in May, will deliver remarks following the policy decision. Market observers will scrutinize commentary for indications of how elevated oil prices might influence monetary policy trajectory.
Prior to the conflict, market pricing reflected anticipated rate reductions during the latter half of 2025. ING analysts suggest the Fed may now communicate postponement of those adjustments.
Below-average winter temperatures combined with recent market dynamics are positioned to bolster energy trading results for the opening quarter, according to JPMorgan’s assessment.



